Buy Property in Dubai
Buying property in Dubai, with advice attached.
Buying a home in Dubai is a bigger decision than the transaction cost suggests. This is what we walk buyers through before they even shortlist.
Start with the job of the asset
A home you’ll live in for a decade, a first Dubai apartment for two years, an eventual retirement address, an investment with rental logic, each has a different “right” community, price band and unit type. We spend our first conversation on this, not on listings.
Where the trade-offs actually sit
A shortlist is a set of trade-offs made explicit: view line vs floor plate, mature building vs new stock, walking access vs quiet street, brand vs price per foot. The right buy is the trade-off you’ll still defend three years later.
- Community fundamentals, tenant depth, supply pipeline, service-charge trend.
- Building-level detail, developer track record, sinking-fund health, layout efficiency.
- Unit-level detail, view line, orientation, floor, layout quirks.
- Transaction structure, cash vs mortgage, timing, negotiating story.
The mechanics
Shortlist, view, offer via Form F MoU with a 10% security cheque, seller obtains NOC from developer, transfer at a DLD trustee office where the new Title Deed is issued. Typical timing on a cash resale is 3–6 weeks; mortgage adds another 3–6.
What usually goes wrong
Buying the community by reputation and the unit by view render. Underestimating service-charge escalation. Not verifying comparable rents at the building level. Skipping a weekday visit at commute hour. All of these are avoidable.
Current launches
Off-plan launches available through Spheron.
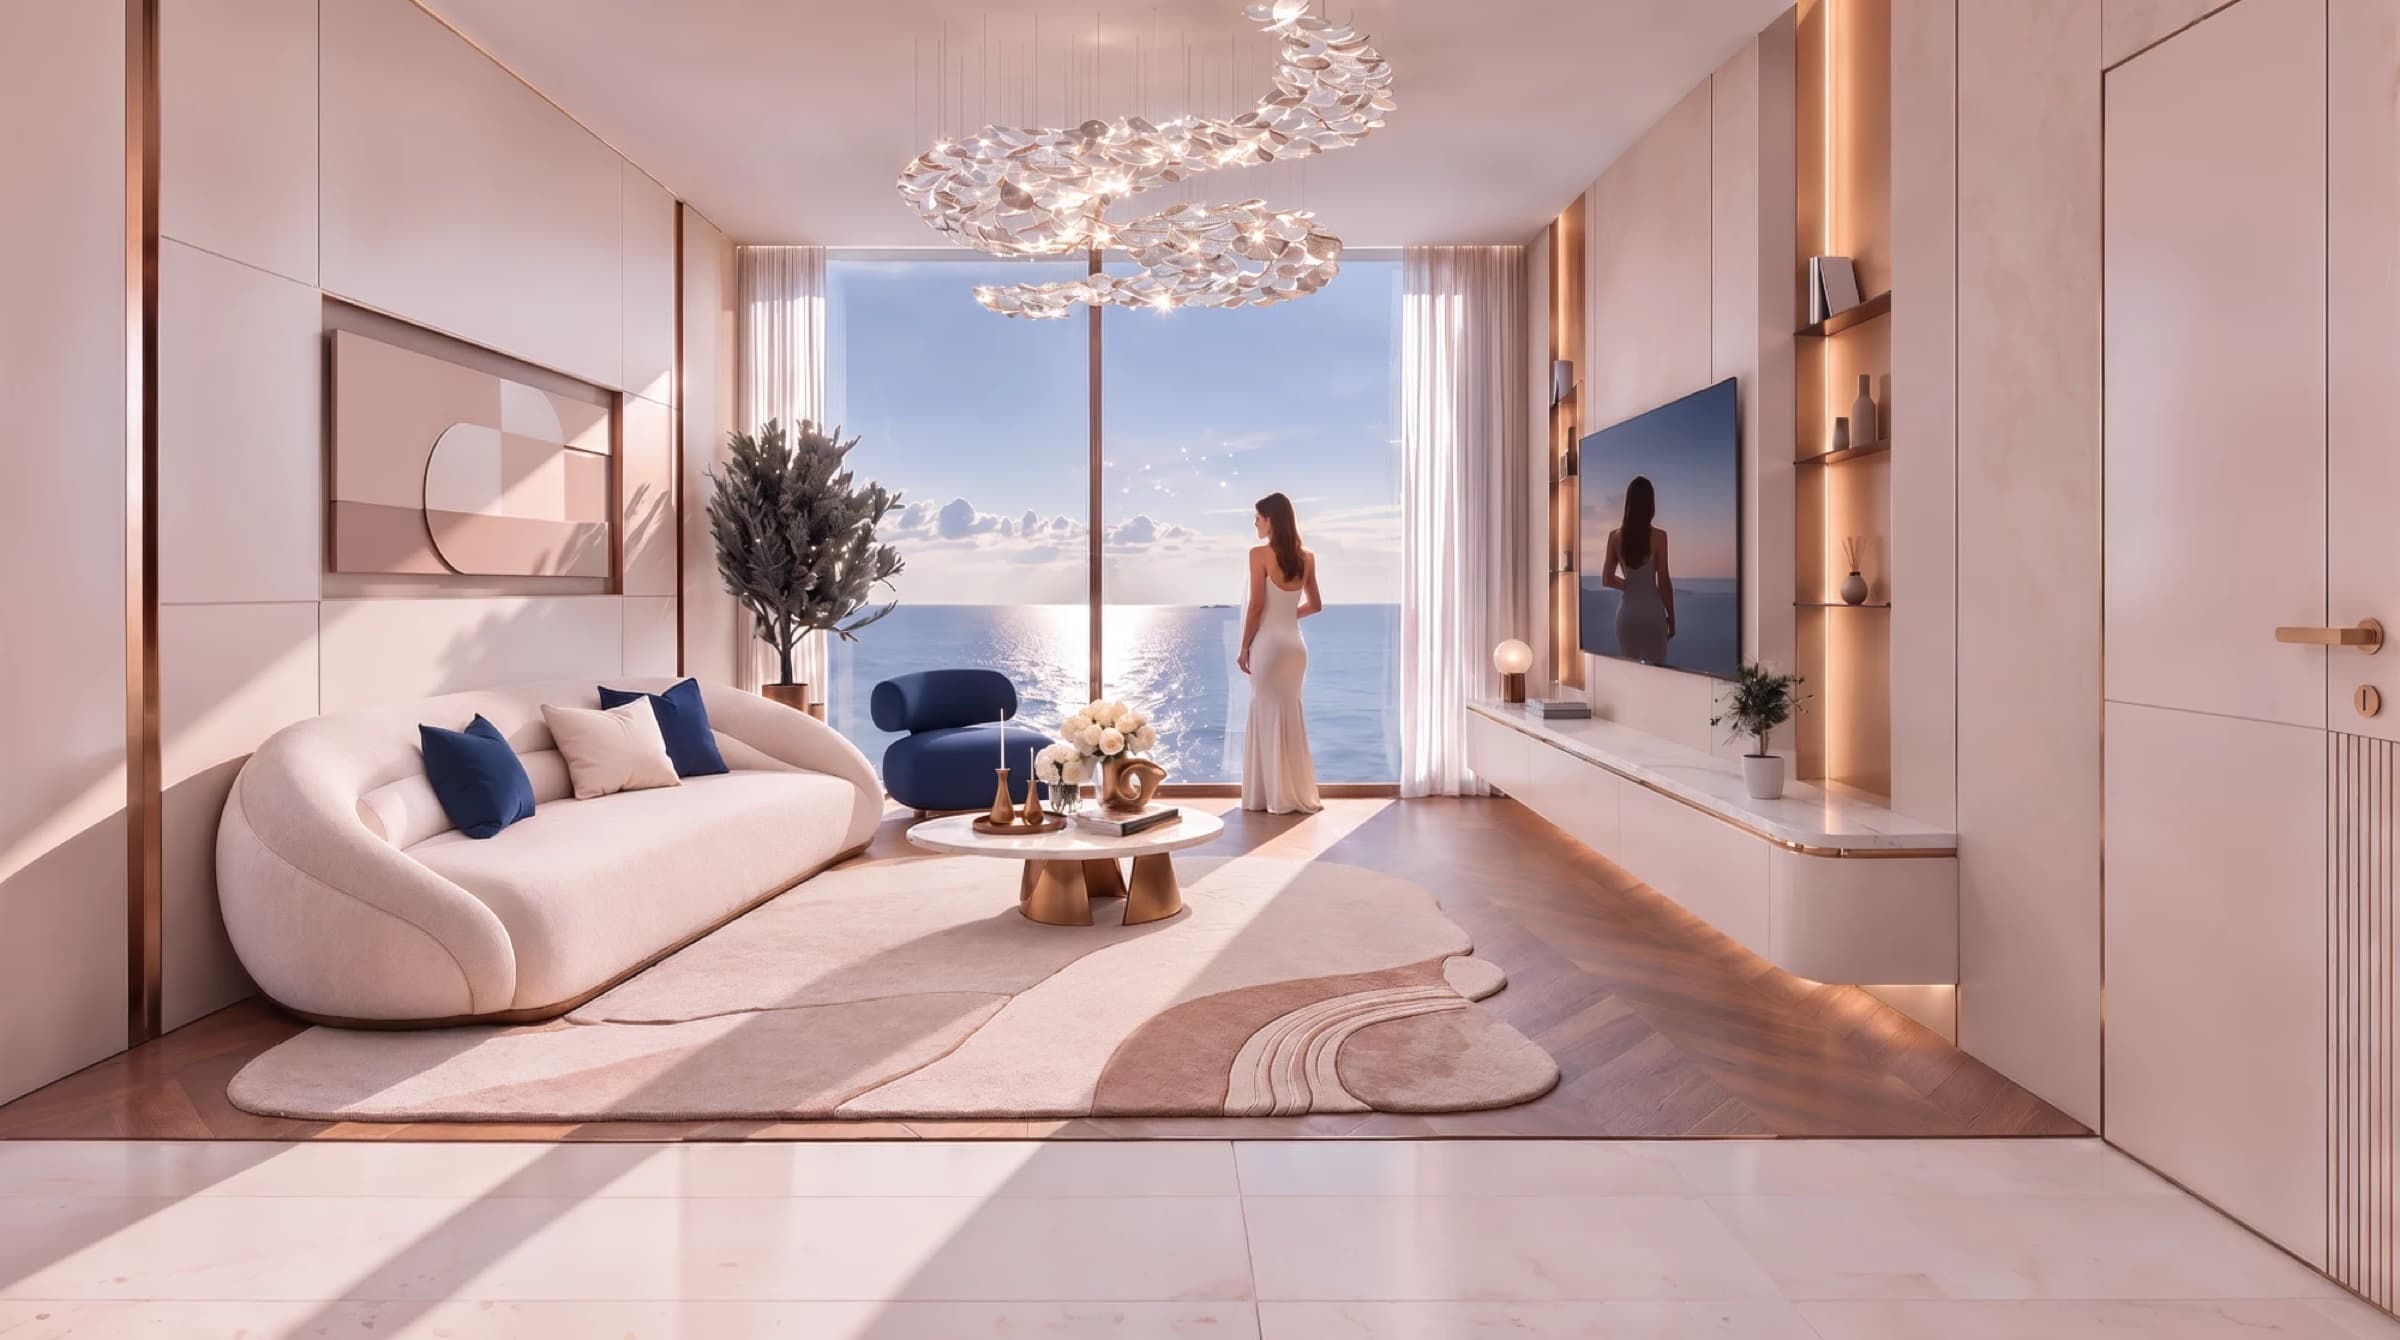
Danube Properties · Dubai Islands
Shahrukhz Residences
From AED 1.5M
1, 2 & 3 BR + Penthouses · Handover Q4 2027
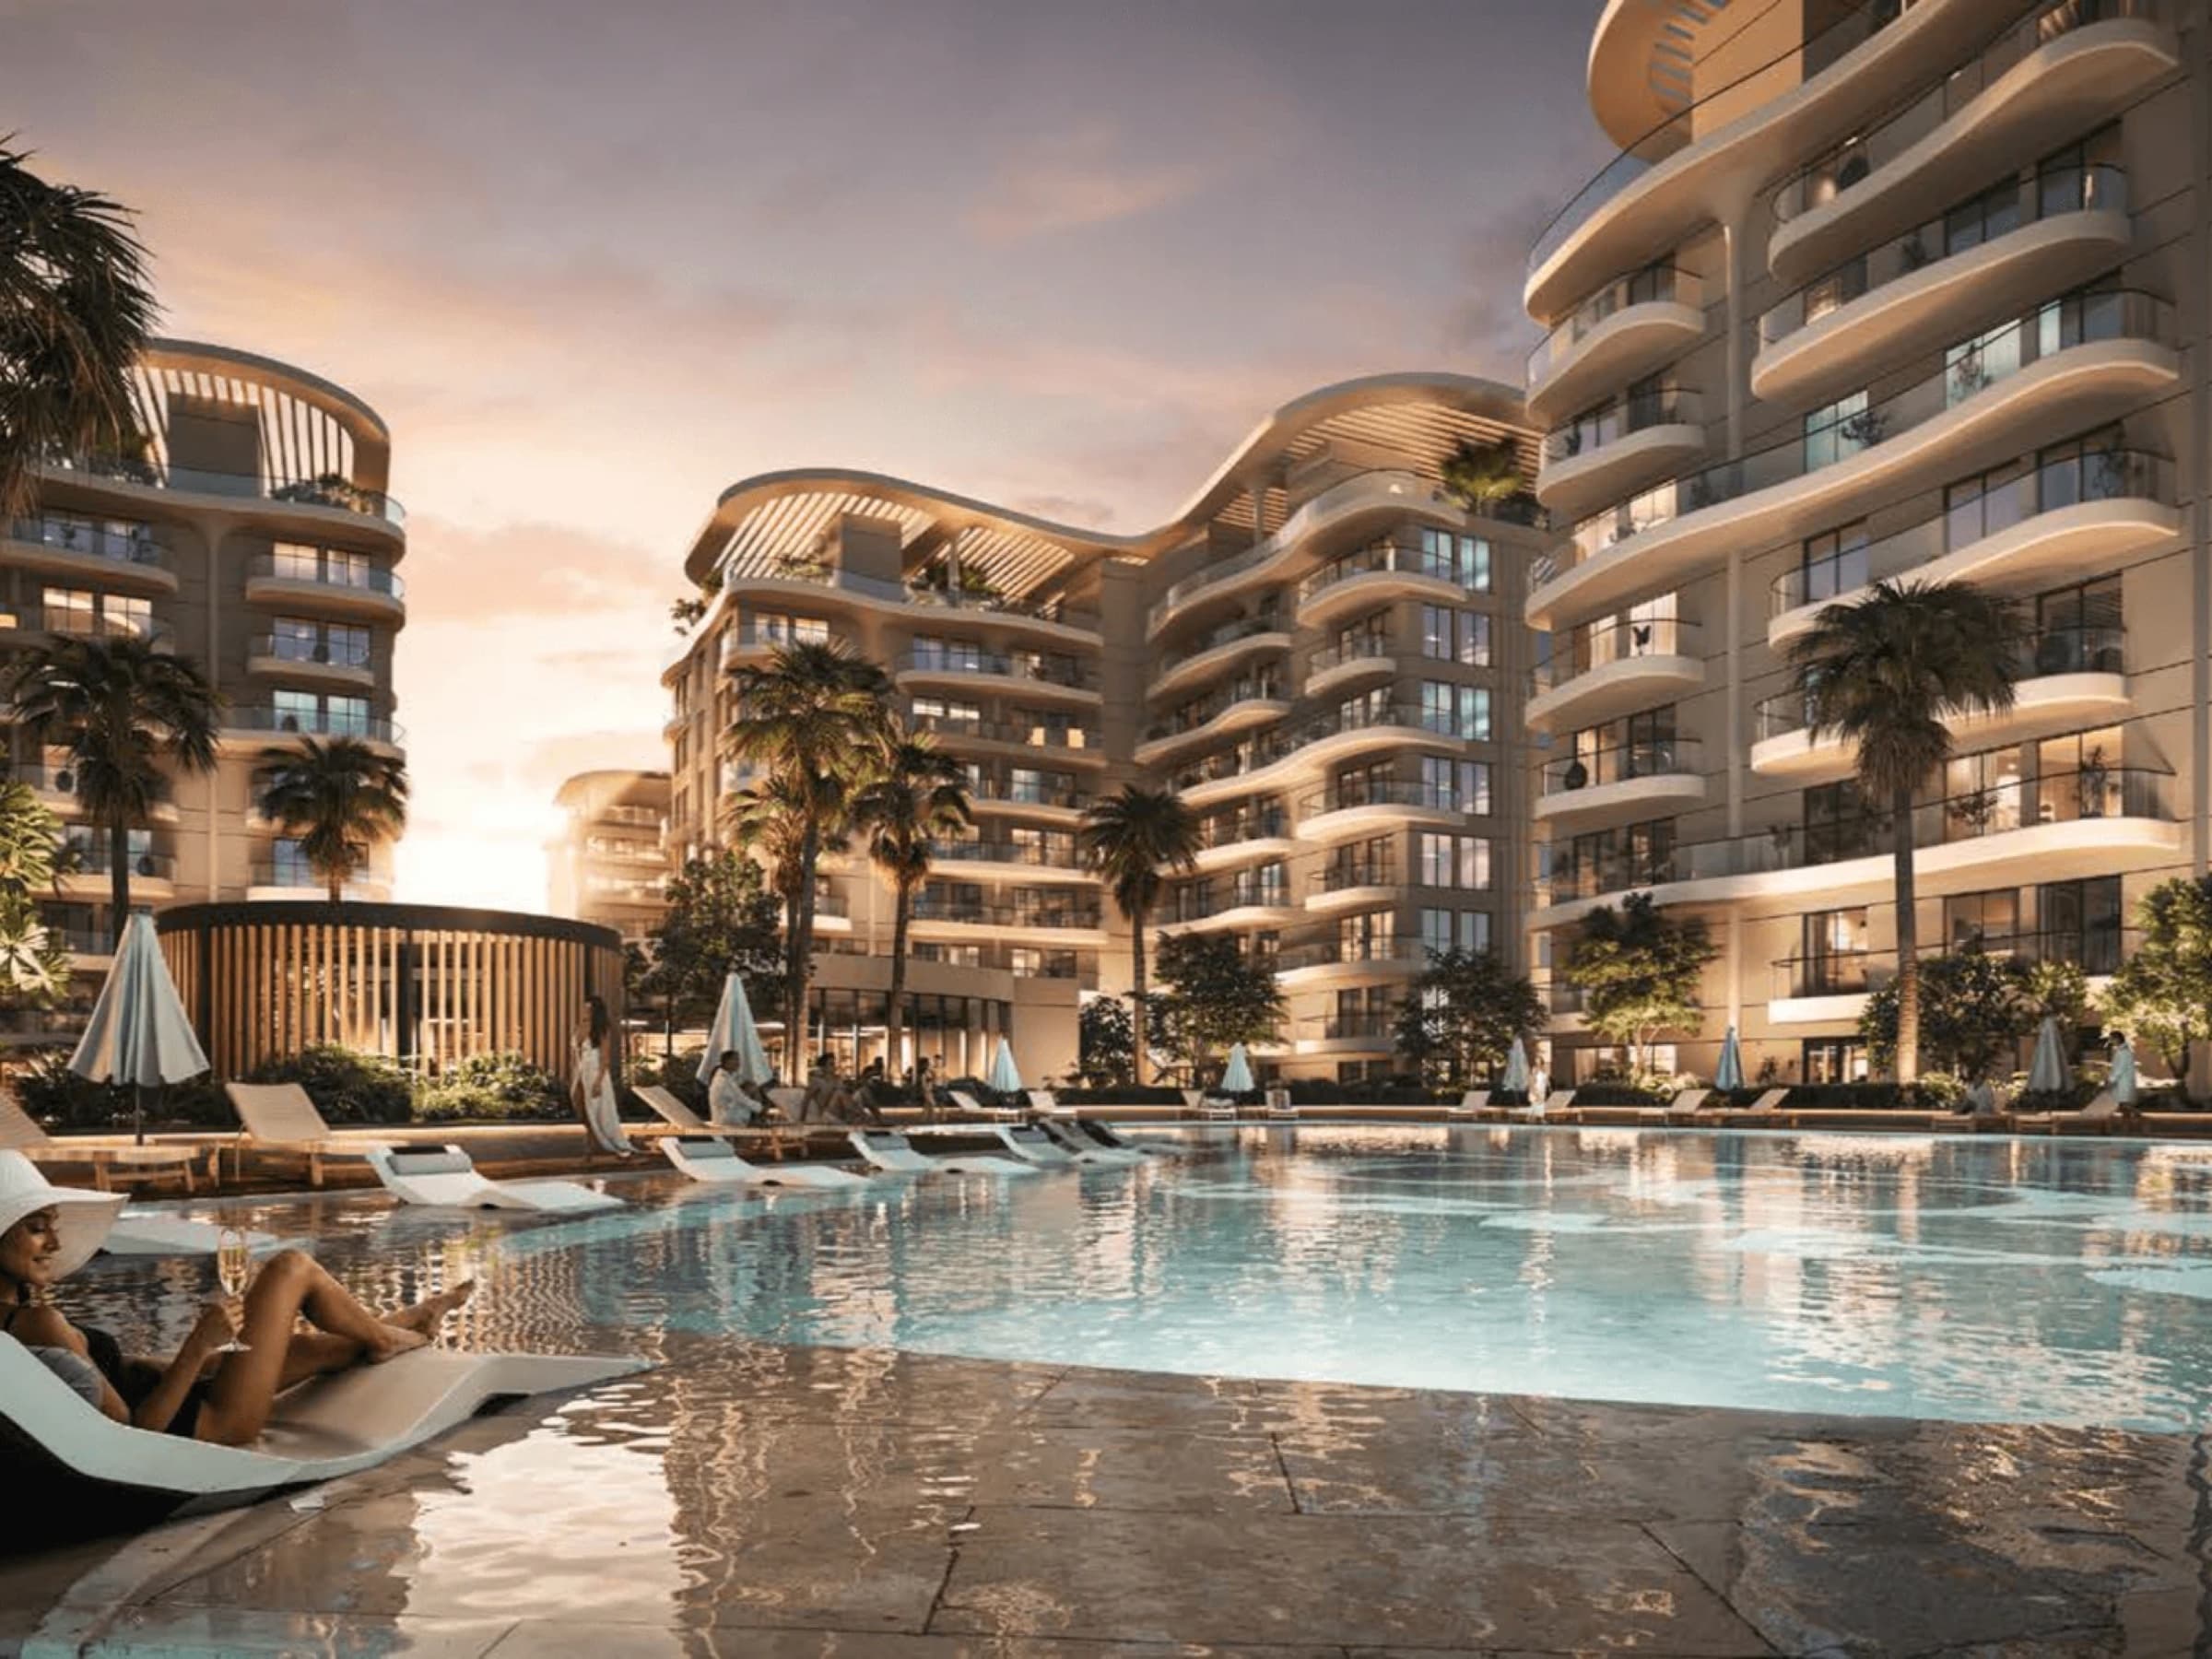
DAMAC Properties · DAMAC Lagoons
Sorrento at DAMAC Lagoons
From AED 1.2M
1 & 2 BR apartments · Handover Q2 2028
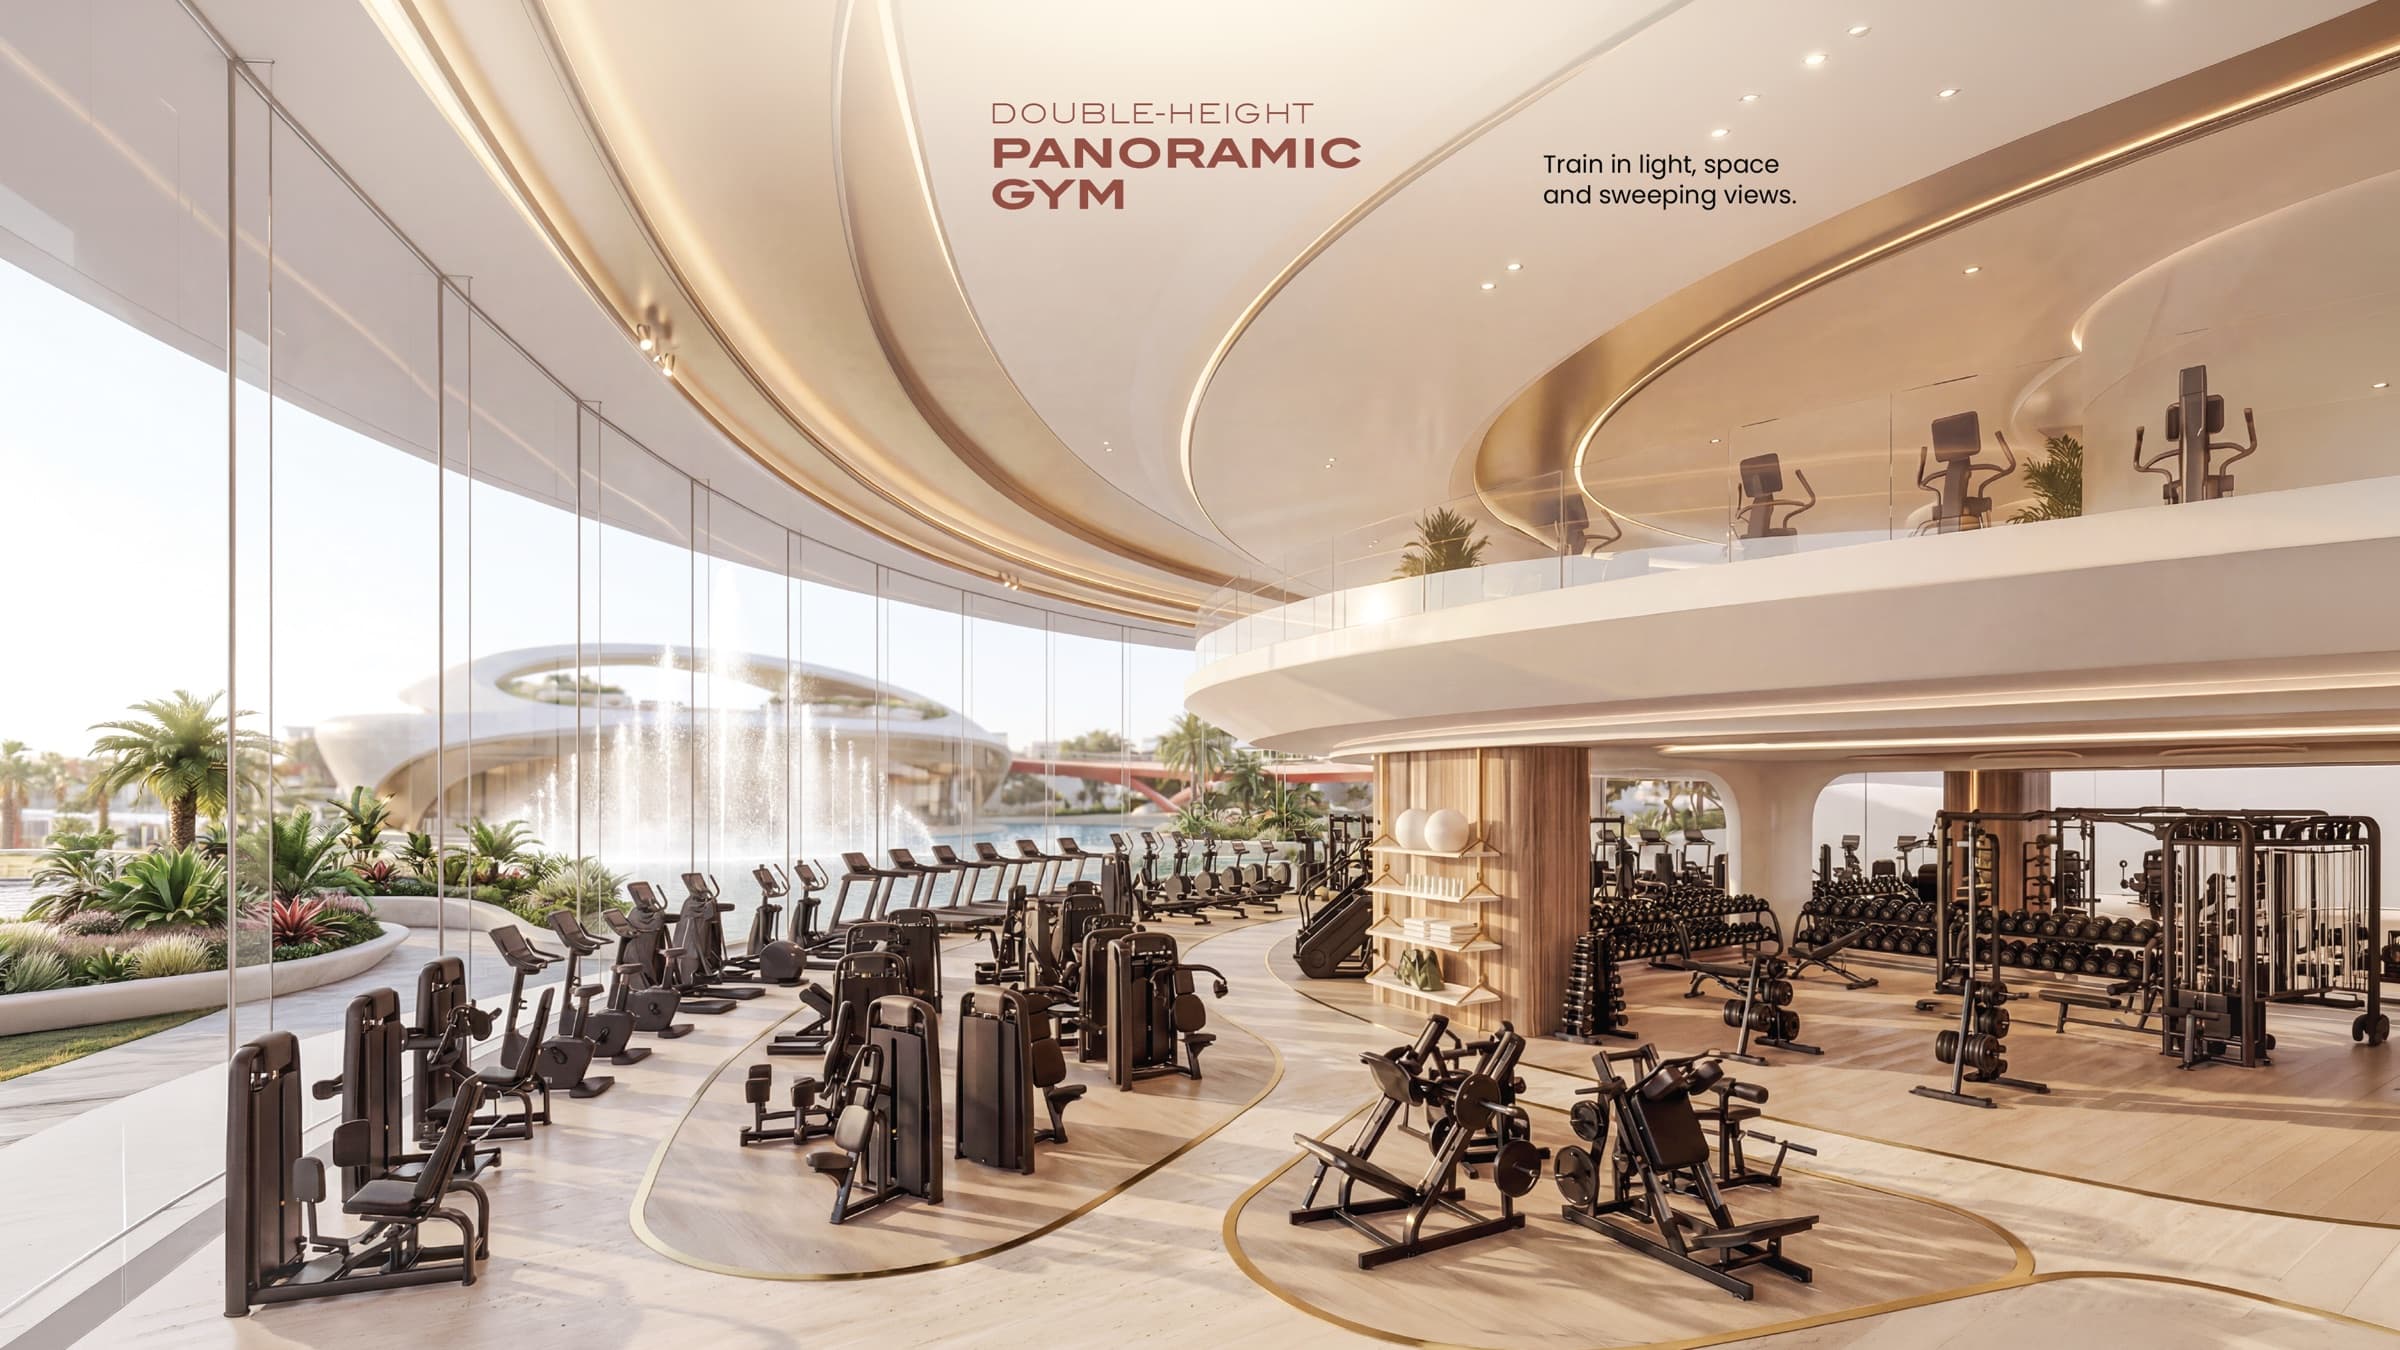
Danube Properties · Dubai Studio City
Greenz by Danube
From AED 900K
Studios · 1 · 2 BR · Handover Q4 2027
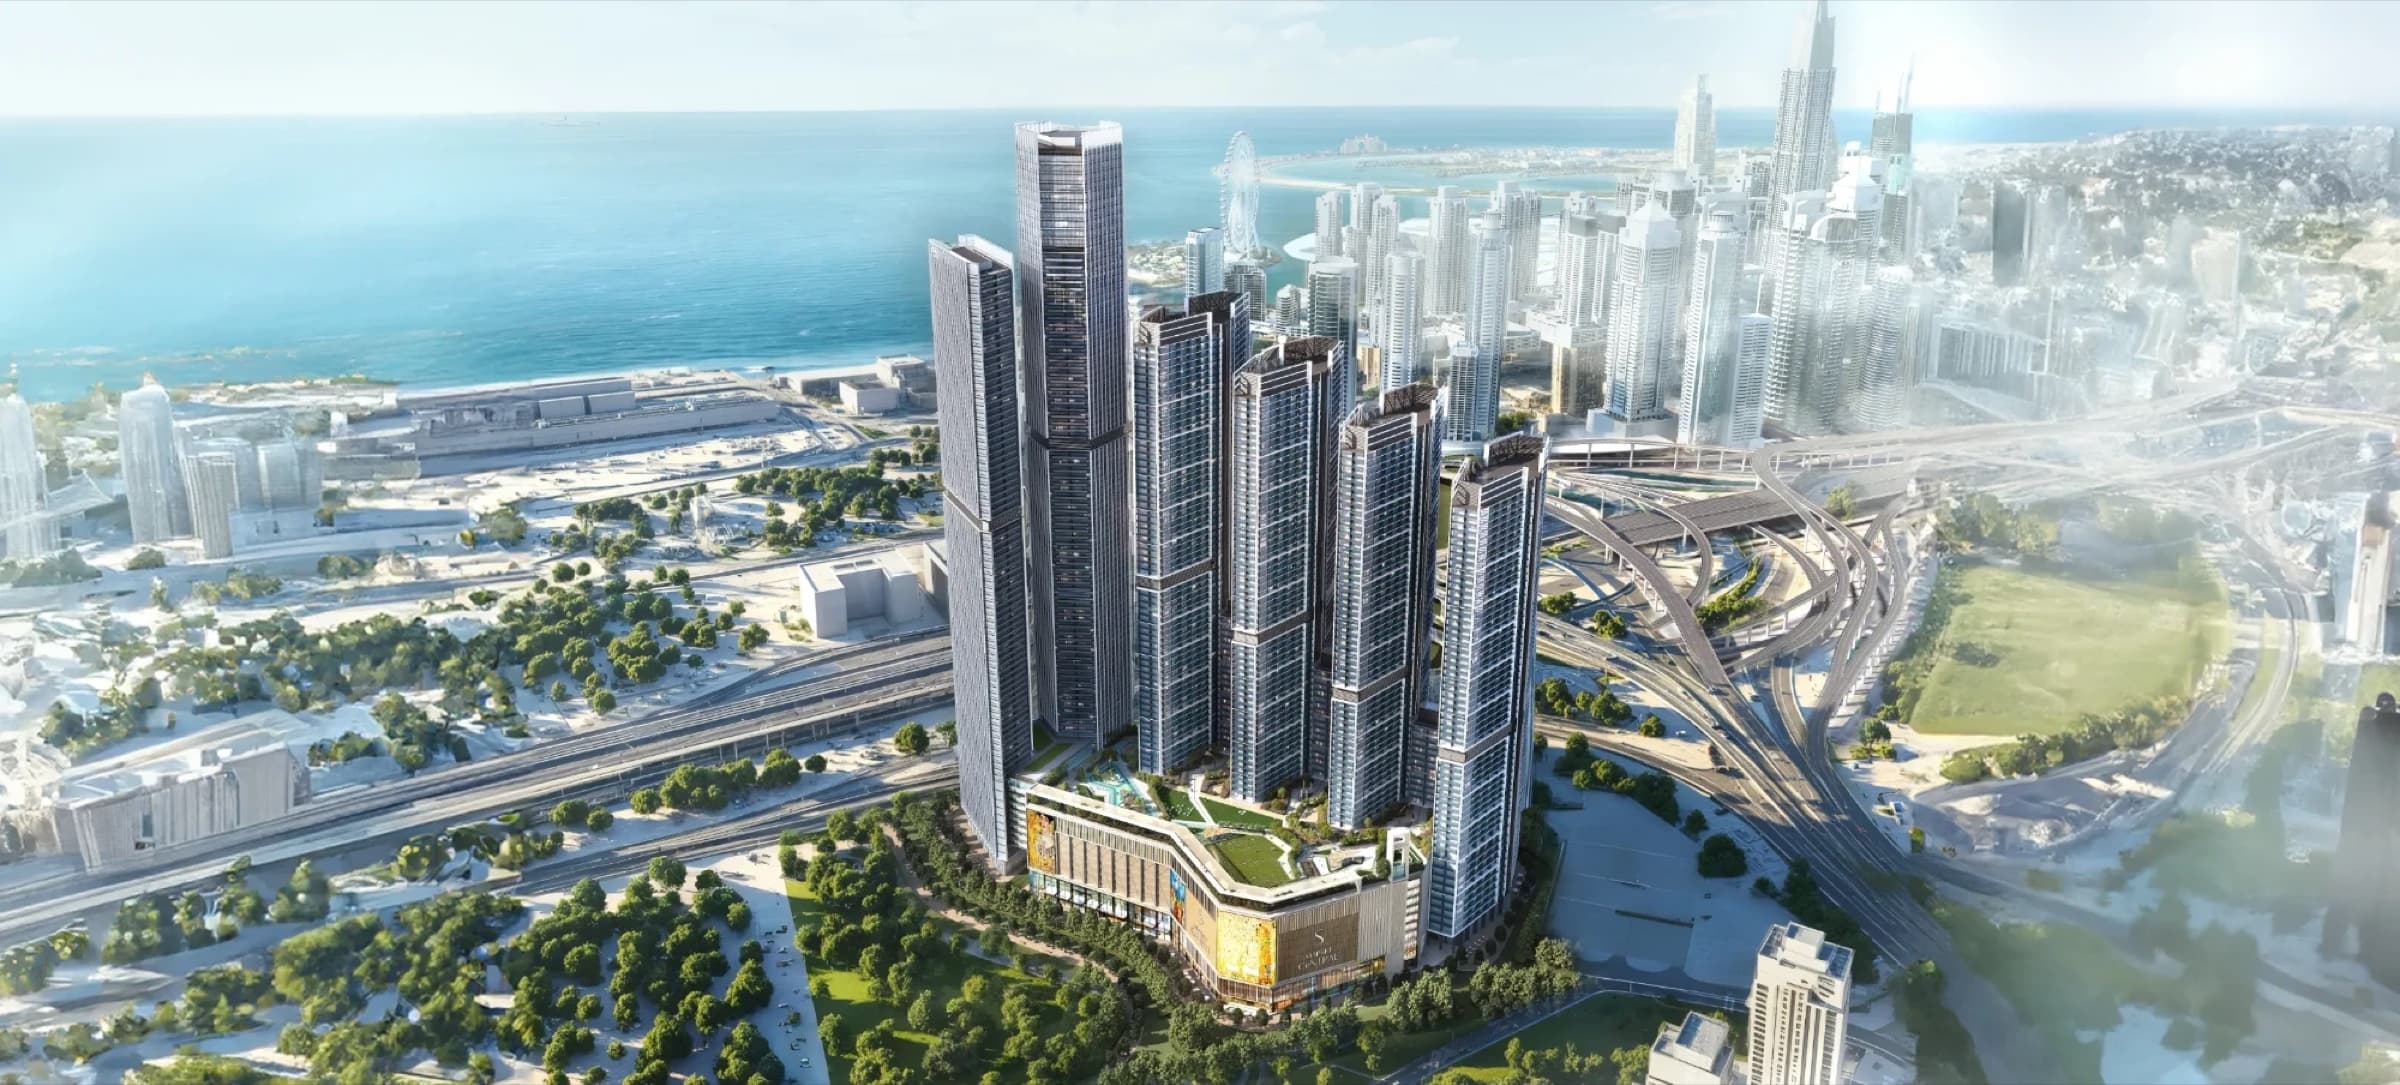
Sobha Realty · Sheikh Zayed Road
Sobha Central
From AED 1.6M
1, 2 & 3 BR + Penthouses · Handover Q4 2029
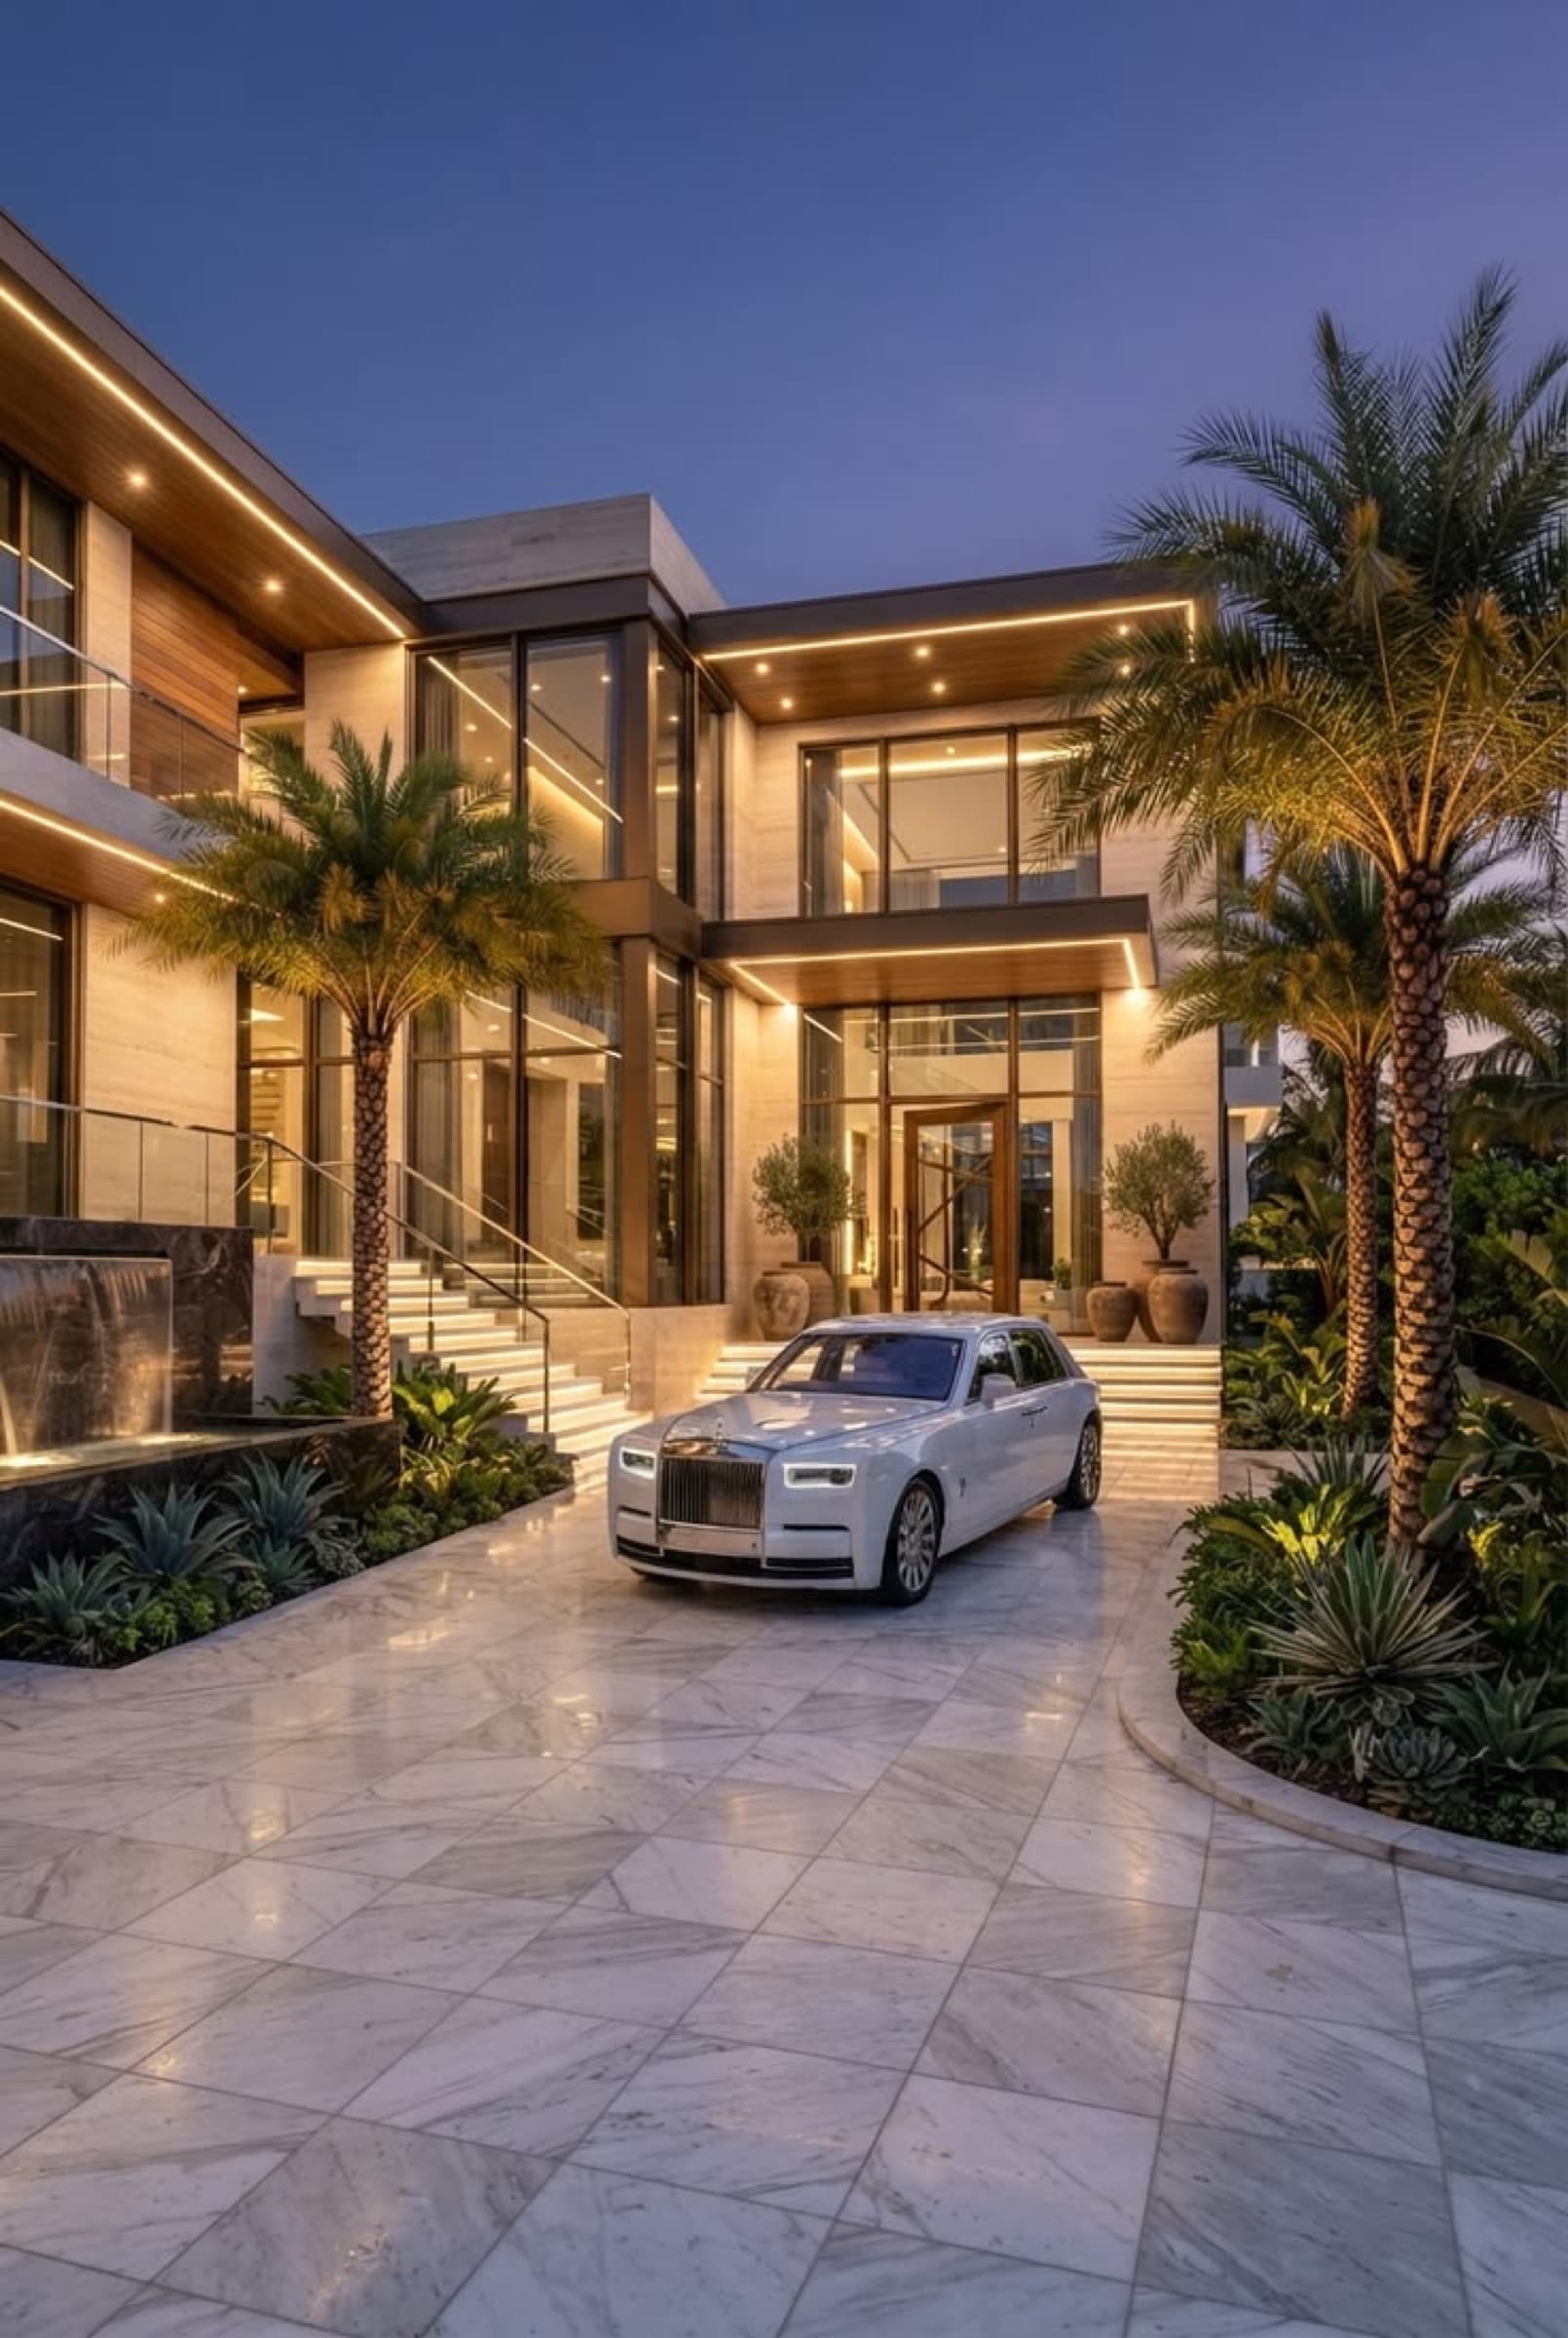
Binghatti · Mohammed Bin Rashid City
Tilal Binghatti
From AED 4.5M
3, 4 and 5 BR residences · Handover Q2 2029
FAQ
Common questions.
Yes, in designated freehold areas. Title Deeds register at the Dubai Land Department. Some communities are leasehold rather than freehold, verify before offering.
Roughly 6–8% of price on a cash purchase (DLD, trustee, agency, NOC). Mortgage adds arrangement and valuation costs.
It depends on the yield you’re underwriting and your rate exposure. We model both scenarios before deciding, not after.
Cash resale, 3–6 weeks. Mortgage, another 3–6 for underwriting. Off-plan is on developer-milestone timelines.
Talk to an advisor